You have been thinking about increasing your prices for months. Supplier invoices are higher, payroll takes up more of the monthly budget, and customers seem to expect more service for the same fee. The business remains busy, but the amount left after expenses feels increasingly disappointing.
Raising prices may help, yet deciding on a percentage without understanding your margins can leave the underlying problem unresolved. Some products may already earn a healthy return, while others consume more resources than their prices allow. A general increase could also disappear through discounts, additional work, or higher delivery costs.
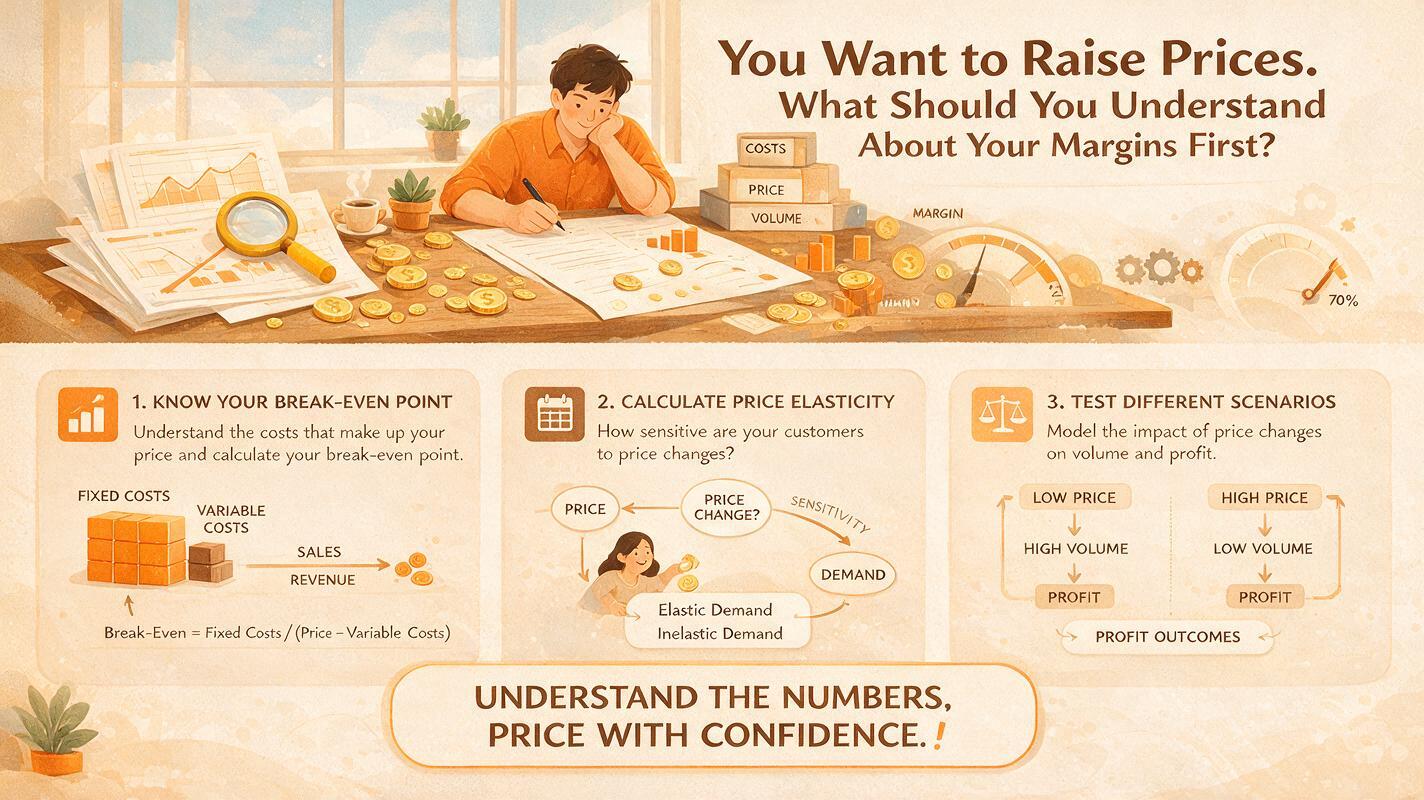
Before announcing new prices, establish what your business currently earns from its sales and what you need the change to achieve. Clear financial information gives you a stronger basis for deciding where to increase prices, how much to change them, and how to evaluate the result.
Start by Identifying Which Margin You Mean
When someone says a business has a “good margin,” ask which measure they are referring to. Gross profit margin, contribution margin, and net profit margin answer different questions, so using them interchangeably can lead to poor pricing decisions.
Gross profit margin expresses revenue less cost of sales as a percentage of revenue. Contribution considers revenue after variable costs, showing the amount available to cover fixed costs and profit. Net profit reflects the expenses included in the business’s final profit figure. Understand how your accounts classify costs before comparing these measures.
For your pricing review, use consistent definitions and compare like with like. A product with an attractive gross margin might still require substantial selling and support expenditure. Equally, an order that contributes towards existing overheads may be worthwhile even if an arbitrary allocation of those overheads makes it appear unattractive.
Check That You Are Not Confusing Margin With Markup
Margin and markup describe the same price and cost relationship from different starting points. Markup measures profit relative to cost, while margin measures it relative to the selling price. Confusing the two can result in prices that fall short of your intended return.
Consider a simplified example in which an item costs S$80 and sells for S$100, with both figures excluding GST. The S$20 difference represents a 25% markup on cost, but a 20% margin on sales. Adding 25% to cost therefore does not produce a 25% margin.
To achieve a 25% margin using that same S$80 cost, the selling price would need to be approximately S$106.67. The calculation is S$80 divided by 0.75. Before using a target margin in quotations, make sure everyone preparing prices understands the calculation and which costs it includes.
Find Out Why Your Margin Has Changed
A shrinking margin does not automatically mean that every price is too low. It may reflect higher input costs, increased discounting, a shift towards less profitable products, or additional work that customers are receiving without paying for it.
Compare a recent period with a suitable earlier period, allowing for seasonal differences. Look at changes in selling prices, purchase costs, sales volumes, and the mix of products or services sold. Where possible, separate the effect of charging less from the effect of spending more to deliver the same work.
For example, a service business might maintain its published fees while allowing more revisions within each engagement. Revenue per assignment remains unchanged, but delivery time rises. A fee increase could provide some relief, yet clearer limits on included work may also be necessary to prevent the same problem from returning.
Look Below the Company Average
An overall margin can hide significant differences between customers, services, and order types. Before applying the same increase everywhere, examine the areas that contribute most to revenue and the areas that place the greatest demands on your team.
Imagine two customers who each spend S$5,000 a month. One places predictable orders, accepts standard delivery, and rarely needs support. The other places frequent urgent orders, requests customised packaging, and requires repeated changes. Their revenue is identical, but the effort and expenditure needed to serve them may differ considerably.
Start with a manageable review of your largest accounts or most common services. You do not need a complex system before asking useful questions. Identify where the business earns a reasonable return, where the information is uncertain, and where the current arrangement clearly needs attention.
Use Costs That Reflect the Next Sale
Historical accounts help explain past performance, but a new price also needs to reflect the conditions under which future work will be delivered. If your supplier has announced a cost increase, relying entirely on last quarter’s purchase prices may produce an outdated calculation.
Review current supplier quotations, freight charges, subcontractor rates, and other costs relevant to the proposed work. For a service business, consider whether the team can complete the assignment within the quoted hours and whether specialist assistance will be required.
Be careful about how costs behave. Existing salaried staff may have spare capacity for additional work, while a larger volume could eventually require another employee. Document these assumptions so that a price calculated for a small increase in activity is not automatically treated as suitable for a much larger expansion.
Give Discounts and Free Extras Their Own Review
Your published price is only the starting point. What matters financially is the revenue you actually retain after discounts, credits, rebates, and concessions, together with the cost of fulfilling the promise made to the customer.
Suppose you increase a quoted fee from S$1,000 to S$1,100, then allow a S$100 discount to secure the order. The customer is still paying the previous amount. If the team also includes additional work to soften the increase, the financial outcome could be worse than before.
Review who can approve discounts and what they receive in return. A lower price linked to a reduced scope, predictable order schedule, or larger committed volume is different from an unexplained concession. Give employees clear guidance so that the intended improvement survives the quotation and negotiation process.
Calculate What Happens if Volume Falls
One concern about increasing prices is losing customers or orders. You cannot predict the response with certainty, but you can calculate how different outcomes would affect contribution under stated assumptions.
Consider an illustrative product selling for S$100 with variable costs of S$60 per unit. At 1,000 units a month, revenue is S$100,000 and total contribution is S$40,000. Increasing the price to S$110 raises contribution per unit from S$40 to S$50, assuming variable costs remain unchanged.
At the new price, selling 800 units would generate the same S$40,000 contribution. In this simplified scenario, a 20% reduction in volume would leave the amount available for fixed costs and profit unchanged. This is a calculation of financial sensitivity, not a forecast that customers will accept the increase.
Real conditions may differ. Lower purchasing volumes could affect supplier discounts, customer losses could change the product mix, and some costs may rise. Use several scenarios and state the assumptions behind each before drawing conclusions.
Consider Capacity Alongside Sales Volume
A business operating close to capacity faces a different decision from one with substantial unused resources. If your team is fully occupied with low-return work, winning additional orders at the same prices may leave little room for more valuable opportunities.
For example, a consultancy might compare the contribution generated by different assignments with the delivery hours each requires. A large engagement may produce more total contribution but occupy the team for considerably longer. Understanding both figures helps explain why a busy schedule does not always produce satisfactory results.
However, avoid treating every hour or order as interchangeable. Some engagements build useful expertise, provide predictable work, or support an important customer relationship. Make those benefits explicit and review whether they justify the financial trade-off.
Set a Clear Objective for the Increase
A pricing change is easier to evaluate when you know what it is intended to achieve. You might want to recover a specific cost increase, restore the return on a service, support additional staffing, or reduce demand for work that strains limited capacity.
Turn that intention into a financial estimate. If you want to fund another employee, consider the full expected employment cost and the additional revenue or contribution needed. If you want to recover higher material costs, identify which products are affected and by how much.
Avoid choosing a percentage simply because it feels modest enough to avoid objections. A small increase that leaves a service financially unsustainable may postpone the same decision. Equally, a large increase without a clear understanding of customer value and alternatives may expose the business to unnecessary commercial risk.
Match the Pricing Approach to the Problem
A blanket increase is one option, but your review may point towards more specific changes. You might adjust selected products, introduce a minimum order value, charge separately for urgent delivery, or define clearer service packages.
For instance, a service provider could retain a standard package with a specified number of revisions and quote separately for additional work. A distributor could review whether small, frequent deliveries justify the same terms as consolidated orders. Each approach addresses a particular cost or demand pattern.
Keep the resulting structure understandable. Customers should be able to see what is included and what triggers an additional charge. Your own staff also need to apply the arrangement consistently, otherwise a more detailed price list can create administrative work without improving margins.
Prepare the Customer Conversation
Knowing your margins gives you confidence in the decision, but customers will usually assess the increase against the value they receive and the alternatives available. Prepare an explanation that is clear, relevant, and consistent with the service you actually deliver.
Specify the new price, its effective date, and any changes to the scope or package. Review existing agreements and commitments before deciding how and when revised terms can apply. Give your team a shared explanation so that customers do not receive conflicting messages.
Plan how to respond to customers who cannot accept the revised price. A smaller package, less frequent delivery, or reduced scope may offer a workable alternative. Assess each option financially rather than automatically restoring the old arrangement whenever a customer objects.
Watch Cash Collection as Well as Profitability
A higher selling price does not necessarily put cash into the bank sooner. Customers may negotiate longer payment terms, take more time to approve invoices, or dispute charges they did not understand.
Include payment timing in your review. If a customer accepts the new price only in exchange for a longer credit period, consider the funding implications alongside the additional margin. The commercial value of the agreement depends on both the amount earned and the resources needed to support it.
Keep quotations, customer approvals, and invoices aligned. Where a price change applies at renewal or to new orders, record that distinction clearly. Accurate administration helps prevent avoidable credits and collection delays from eroding the expected benefit.
Measure What Happens After the Change
Once new prices take effect, compare actual results with your assumptions. Review realised selling prices, order volumes, discounts, relevant costs, customer retention, and the contribution generated over a meaningful period.
Separate customers already paying the new rate from those still on previous agreements. Otherwise, the transition may make the overall figures difficult to interpret. Also consider seasonal changes and other developments that could explain movements in sales or profitability.
Decide in advance when management will review the outcome. If revenue rises while contribution remains disappointing, investigate the reason before making another adjustment. You may discover that discounting increased, costs moved again, or customers shifted towards a different mix of services.
Build the Decision on Reliable Financial Information
Kazuma Public Accounting Corporation provides bookkeeping, accounting, and monthly or quarterly financial reporting for businesses in Singapore. For companies with a budgeting system, its services can also include budget-to-actual analysis as needed.
Reliable reporting provides a foundation for understanding how revenue and expenses are changing. A detailed pricing review may also require operational information, such as delivery hours, order frequency, or customer support demands. Bringing these records together helps management ask more precise questions about profitability.
Before your next price increase, review the current return, identify the reason for any deterioration, and test a few realistic outcomes. Then choose a pricing approach that addresses the problem and establish how you will measure its effect. The aim is to understand whether the work you sell provides a sustainable return for the resources your business commits.