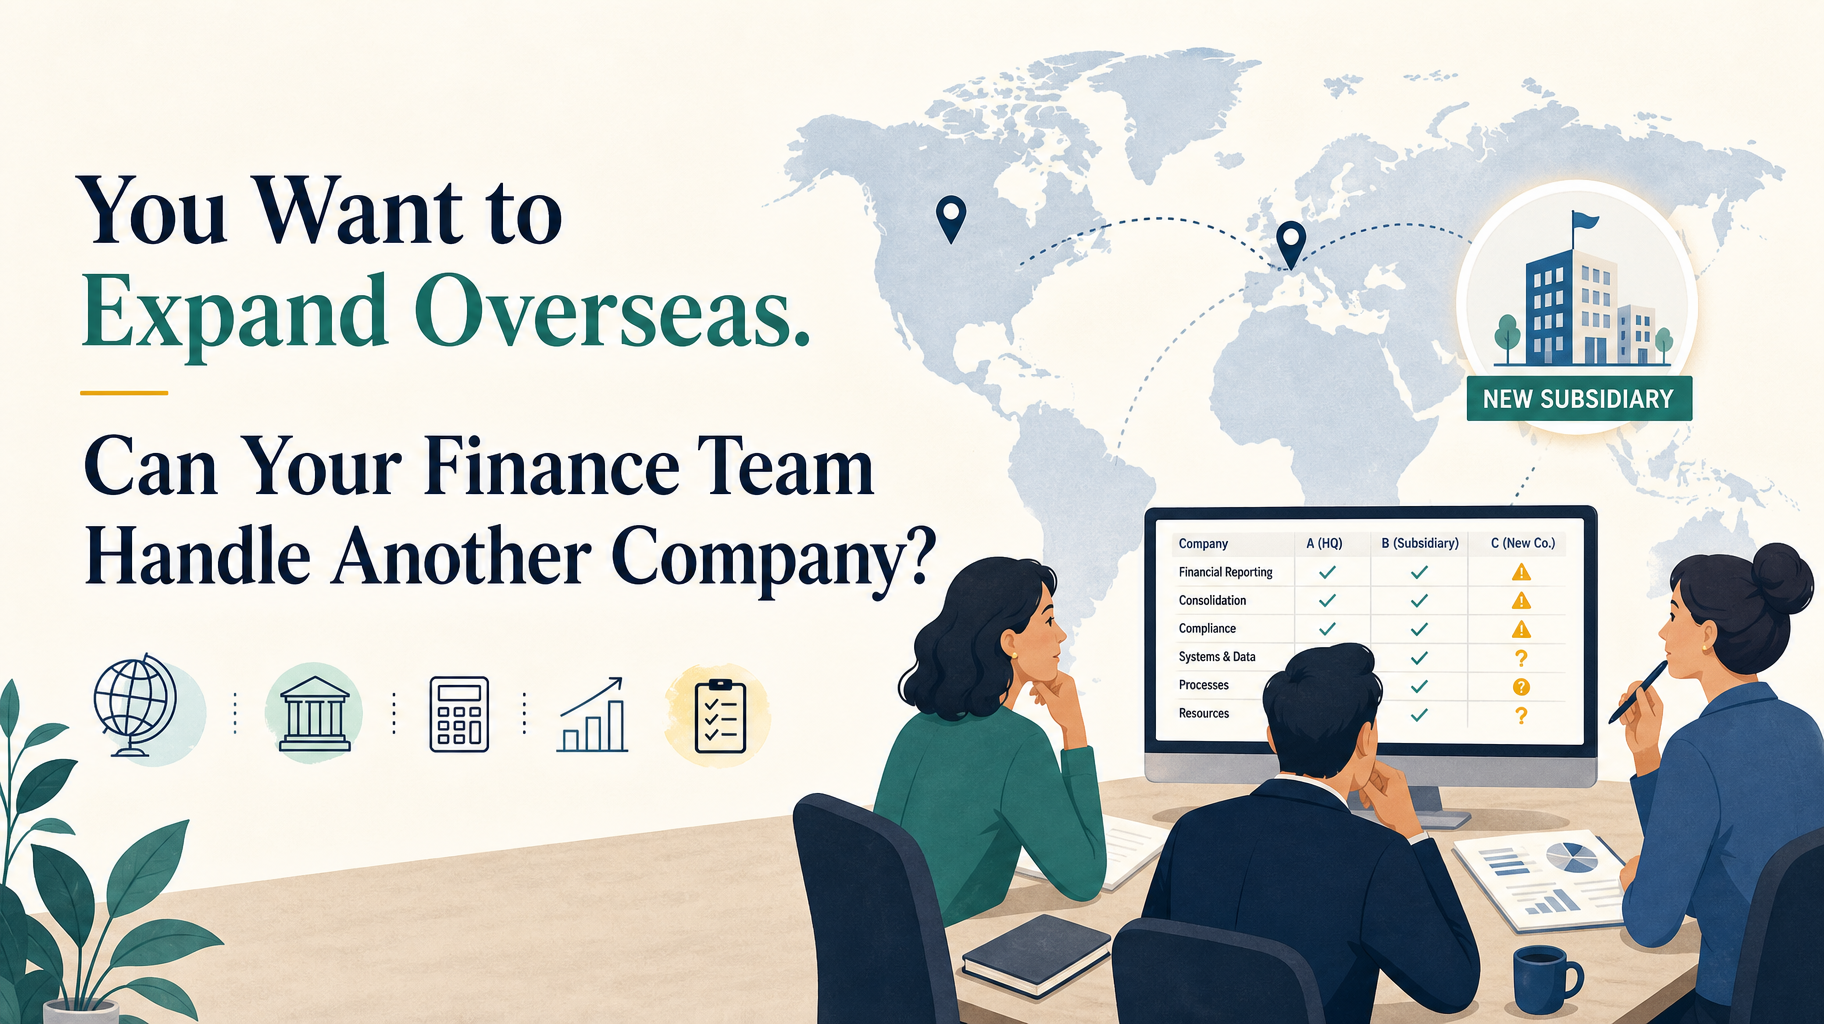
Opening an overseas company can feel like a natural next step for a growing business. You have identified a promising market, found potential customers, and started discussing premises, recruitment, or local partnerships. The commercial opportunity is becoming clearer, and attention quickly turns to getting the new operation running.
Meanwhile, the finance team may receive a much shorter brief: set up the accounts, arrange payments, and include the new company in the monthly reports. That request can hide a substantial change in responsibility. Another company brings another set of records, balances, approvals, deadlines, and questions that management needs someone to resolve.
Before committing to expansion, consider whether your finance function can support the structure you are creating. The answer involves more than headcount. It requires clear responsibilities, usable information, and a reporting process that helps you understand what is happening in each business.
Start With the Decisions You Need Finance to Support
Begin by identifying what you will need to know once the overseas operation opens. You may want to monitor its spending against the launch budget, understand how long its funding will last, or decide when to recruit additional employees. Those questions should influence the information collected from the beginning.
For example, if the expansion plan assumes that the new company will support itself within twelve months, a total monthly expense figure will provide limited insight. You will also need to understand customer receipts, upcoming commitments, and the reasons actual performance differs from the plan.
Write down the decisions that management expects to make during the first year. Then establish which reports, records, and explanations would support them. This gives the finance team a concrete brief and helps prevent a reporting process built entirely around whatever information happens to be available.
Look at Your Existing Team’s Capacity Honestly
An expansion plan often assumes that the current finance team can absorb the extra work until the overseas business becomes larger. That may be practical, but only if the assumption reflects the team’s actual workload and the complexity of the new operation.
Review the existing monthly routine. Consider how much time goes into processing transactions, resolving missing documents, reconciling balances, preparing reports, and answering management questions. If these activities already depend on overtime or one person’s memory, the additional company may expose weaknesses that were previously manageable.
Capacity also includes review and problem-solving time. Entering another set of invoices may be straightforward, while investigating an unexplained balance across two companies can take much longer. Allow room for unfamiliar transactions, coordination with advisers, and the additional questions that arise during a launch.
Decide Who Owns Each Part of the Work
A common source of confusion is assuming that appointing a local accounting provider transfers responsibility for the entire finance process. The provider may prepare records from information supplied, while someone within the business still needs to approve payments, explain transactions, and collect supporting documents.
Set out who will handle daily bookkeeping, bank reconciliations, payroll coordination, management reporting, and communication with local advisers. Identify who reviews the work and who follows up when something is missing. Each recurring task should have an owner and a clear route for resolving questions.
Imagine an overseas manager approving a supplier invoice while the Singapore finance team controls payment. Unless the handover is defined, each side may assume the other has checked the invoice details or retained the documentation. A simple written process can prevent that uncertainty from becoming a recurring payment problem.
Make Reporting Comparable Across Companies
Your overseas company may use a different accounting system or work with a provider whose reports follow a different structure. Those arrangements can still work, provided the information can be translated into a consistent format for management review.
For example, one company might record delivery expenditure under distribution costs while another includes it within cost of sales. If management compares their gross margins without understanding that difference, the reports could suggest a performance gap that partly reflects classification.
Agree on the categories and definitions that matter to the group. A practical mapping between local accounts and the parent company’s reporting format can be more useful than immediately forcing every operation onto identical software. The priority is that the information can be explained, reconciled, and compared consistently.
Build a Reporting Calendar That People Can Meet
Management may want a complete group report five working days after month-end. Before promising that deadline, work backwards through the activities required to produce it.
Bank information needs to be available, transactions need to be recorded, balances need to be checked, and questions need to be resolved. The overseas team may also depend on information from payroll providers, inventory staff, or operational managers. A deadline imposed without considering these dependencies can result in repeated estimates or incomplete reports.
Create a calendar that includes submission, review, and correction time. Specify what each company must deliver and when the parent team will raise questions. If an early report contains estimates, make them visible and establish how subsequent adjustments will be communicated.
Plan for Transactions Between the Companies
Once the overseas operation begins, money and resources may move between it and the Singapore business. One company might pay a software subscription used by both, fund an initial purchase, or provide staff support to the other.
These transactions need clear records on both sides. If the Singapore company records an amount due from the overseas company, the overseas records should reflect the corresponding arrangement appropriately. Differences caused by timing, currency, or inconsistent treatment need someone to investigate them.
Consider a hypothetical S$20,000 payment made by the parent for the new company’s equipment. Before month-end, the finance team should understand what was purchased, which entity owns it, how the payment was funded, and how the transaction has been recorded. Waiting until year-end makes the explanation harder to reconstruct.
Cross-border arrangements can also raise accounting, tax, and documentation questions. Identify these early and obtain advice appropriate to the jurisdictions and transaction, rather than assuming that an internal transfer requires no further consideration.
Distinguish Local Reports From Group Reporting
A set of accounts prepared for the overseas company may not contain everything the parent needs. Management might require a particular expense breakdown, supporting schedules, or explanations of significant movements that are absent from the local reporting package.
Group reporting may also require accounting adjustments, currency translation, and the appropriate elimination of transactions and balances within the group. The applicable treatment depends on the reporting framework and circumstances, so responsibility for these tasks should be agreed with the relevant accounting advisers.
Ask for a sample reporting package before the new company starts operating. Working through the required schedules in advance can reveal missing information while it is still easy to change the process. It is much harder to recreate several months of detail after management discovers that the original reports are insufficient.
Separate Profit Monitoring From Funding Decisions
The overseas operation may be expected to make losses during its launch period, but that does not tell you exactly how much cash it will require. Deposits, equipment purchases, customer payment timing, and other commitments can create funding needs that differ from the reported monthly loss.
Prepare a cash forecast alongside the profit budget. Include the expected timing of significant payments and receipts, and identify when additional funding would be needed. Update the forecast as actual arrangements replace initial assumptions.
For example, the budget might assume that customers pay within thirty days, while the first major contract provides for payment after a longer acceptance process. Even if the contract is commercially attractive, the timing difference could change the amount of funding required. Management needs that information before the bank balance becomes urgent.
Keep Currency Assumptions Visible
An overseas company may receive income and pay expenses in a currency different from the one used for group reporting. Management therefore needs a clear understanding of how currency assumptions affect budgets, forecasts, and comparisons.
Suppose the local operation’s monthly expenditure remains stable in its own currency, but its reported cost to the parent increases after exchange rates move. Without an explanation, management may interpret the change as an operating overspend and ask the local team to correct a problem it did not create.
Agree on how reporting will distinguish operating movements from currency effects where this is useful. Also consider the currency and timing of planned funding transfers. The finance team should be able to explain the assumptions and identify when they need review, while obtaining specialist advice for more complex currency arrangements.
Preserve Payment Oversight as the Business Grows
Expansion can put pressure on payment controls because the new operation needs to move quickly. An urgent deposit, unfamiliar supplier, or last-minute purchase may lead employees to create temporary workarounds that later become routine.
Establish who can approve expenditure, who can create or amend supplier details, and who can release payments. Where a small team cannot separate every task, decide what additional review is practical. The arrangement should reflect the people available and the level of expenditure involved.
Make sure management can access supporting records and understand significant payments without depending entirely on one person. Clear access arrangements and documented approvals are particularly valuable when staff work across different locations or time zones.
Budget for Finance Support Before the Launch
The cost of supporting another company extends beyond the basic bookkeeping fee. Depending on the proposed structure, the business may need additional reporting support, software access, local professional advice, staff training, or help preparing information for the parent.
Include these items in the expansion budget and clarify which activities are covered by each provider’s engagement. A low initial fee may cover routine transaction processing while leaving management reports, additional schedules, and urgent queries outside the agreed scope.
Compare support options against the work required. Hiring, outsourcing, and combining internal staff with external providers can each be appropriate. The useful question is whether the chosen arrangement supplies the necessary skills, review capacity, and continuity at a cost the business can sustain.
Test the Process Before It Becomes Essential
You can identify many reporting problems before the first live month-end by running a simple rehearsal. Use a small set of hypothetical transactions to test how the companies and their advisers would handle them.
Include an ordinary customer sale, a supplier payment, an expense paid by the parent, and a funding transfer. Ask each person involved to explain what they would record, approve, submit, and review. Then check whether management would receive the information needed to understand the result.
This exercise may reveal an unclear responsibility, missing account category, or unrealistic deadline. Resolving those issues during preparation is easier than doing so while employees are waiting for payment and management is asking for the first performance report.
Connect the Expansion Plan to Kazuma’s Reporting Support
Kazuma Public Accounting Corporation provides accounting and bookkeeping services, periodic financial reporting, parent-company reporting support, and consolidation package preparation support. For companies with budgeting systems, its reporting services can also include budget-to-actual analysis as needed.
These services are relevant when a Singapore business needs a clearer process for managing financial information within a wider group. The responsibilities of Kazuma, the internal finance team, and any overseas advisers should be defined around the proposed structure and reporting requirements.
Before launching another company, bring together the expansion budget, expected transactions, reporting timetable, and proposed division of responsibilities. Review where the current team has capacity and where additional support is required. A workable finance process gives management a better basis for funding the new operation, assessing its progress, and making the next business decision.