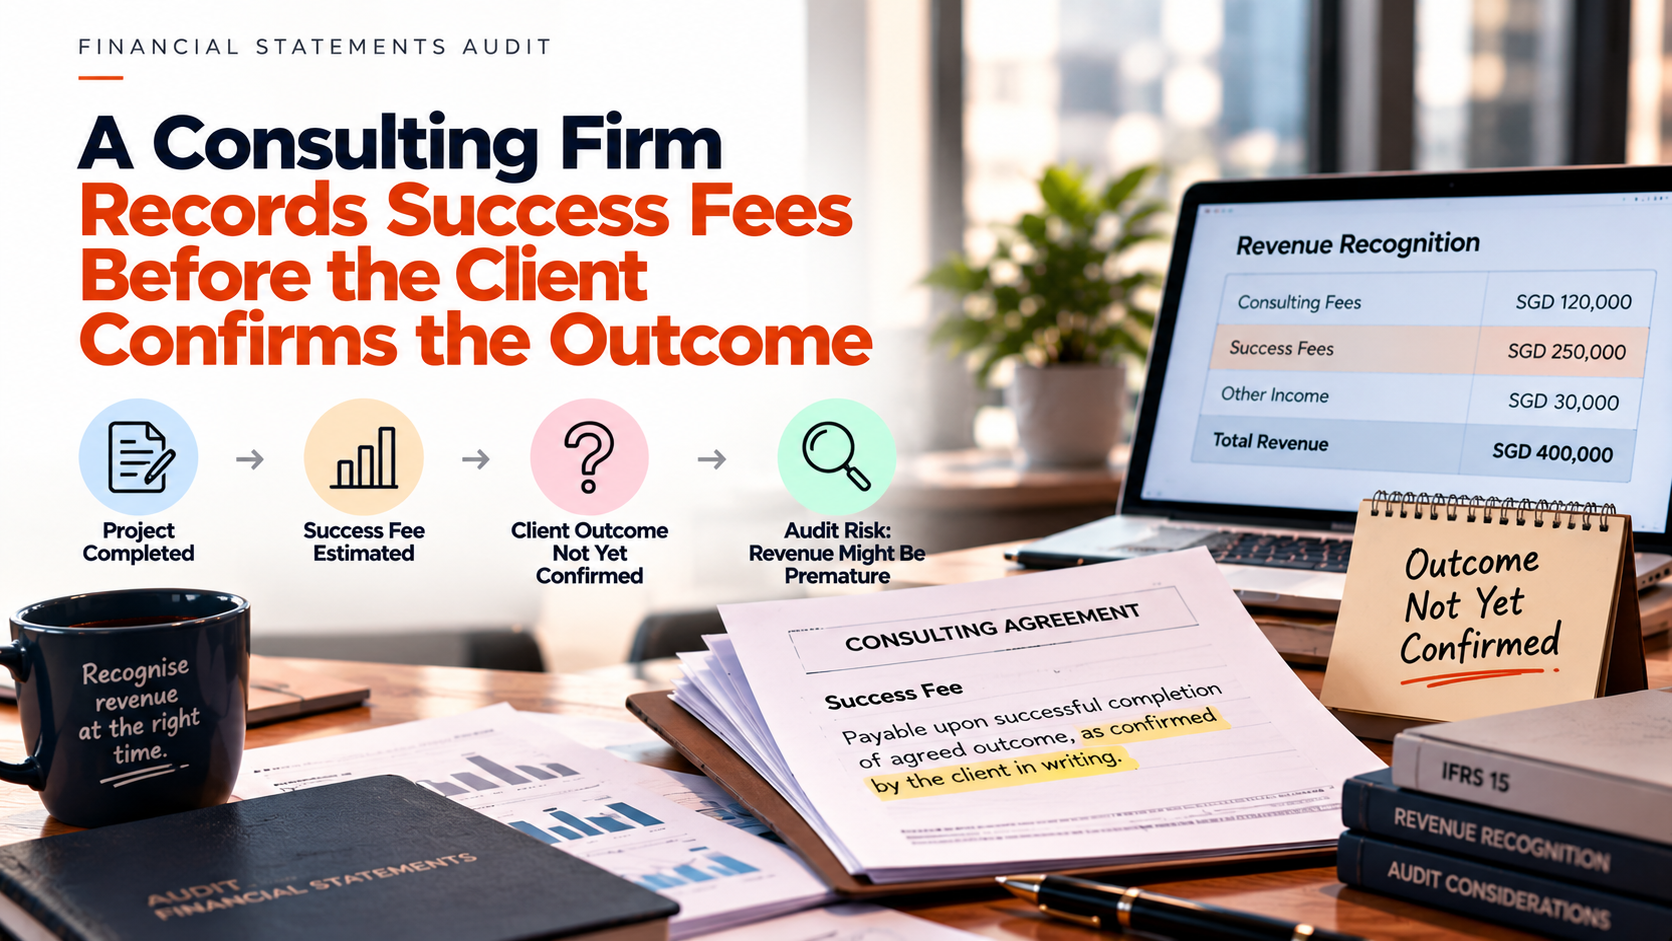
The consulting team believes it has achieved the agreed result. Its final report shows the expected savings, the project manager considers the assignment complete, and management includes the success fee in the year-end accounts. The client, however, has not confirmed the outcome or accepted the fee calculation.
That difference matters. A success fee may depend on measurable results, a transaction completing, a sustained improvement or a client assessment that remains unresolved. The consultancy’s confidence in its work does not, by itself, establish the amount of revenue that can be recognised.
Kazuma provides financial statements audit and accounting services. For consulting firms, preparing a supported revenue position means connecting contractual terms with evidence of performance and the remaining uncertainty. The objective is to explain why the recorded amount belongs in the reporting period, rather than relying on an invoice or an internal forecast.
Start With the Contractual Meaning of Success
“Success fee” is a commercial label that can describe several arrangements. One consultancy may earn a percentage of verified cost savings. Another may receive an additional fee when a financing transaction completes. A third may be paid only if the client achieves a specified operating target.
Identify the exact condition in the agreement. Establish how the outcome is measured, which period is covered and who provides the underlying information. Check whether exclusions, caps or minimum thresholds affect the calculation.
Retain amendments and correspondence that change the original arrangement. A revised target agreed during the project can make the initial engagement letter an incomplete basis for the accounting assessment.
Where the wording is ambiguous, obtain the appropriate clarification or advice. Finance should not create its own definition of success merely because the project team has already prepared a fee estimate.
Separate Work Completed From the Fee Expected
A consultancy can complete substantial work while uncertainty remains over its remuneration. Conversely, an outcome might be achieved while further promised services remain outstanding. The accounting assessment needs to address both performance and the amount of consideration.
Under revenue recognition principles, revenue reflects services transferred to the customer and the consideration the business expects to be entitled to receive. Completing internal tasks does not automatically establish that every contractual promise has been satisfied.
Prepare a summary of the services promised and their status at the reporting date. Identify any remaining implementation, monitoring or reporting work. Explain how management assessed the timing of performance under the applicable reporting framework.
This avoids treating the success-fee calculation as the whole revenue assessment. A mathematically correct amount is not enough if the underlying service or entitlement has not been established.
Apply the Variable Consideration Assessment
Success fees commonly involve variable consideration. The expected value or most likely amount method is used according to which better predicts the consideration, followed by the constraint assessment.
An estimated amount is included only to the extent that it is highly probable that resolving the uncertainty will not cause a significant reversal of cumulative revenue. This involves considering both the likelihood and size of a possible reversal.
Factors outside the consultancy’s influence, limited relevant experience and a long period before resolution can affect that judgement. A strong sales forecast or management’s preferred probability percentage does not replace the required assessment.
Document why the recorded amount meets the requirements. Where uncertainty remains too significant, the outcome may differ from the commercial pipeline value even though management still expects the project to succeed.
Determine Whether Client Confirmation Is Substantive
The absence of a signature does not automatically prevent recognition in every arrangement. Equally, describing approval as “administrative” does not make it so.
Acceptance may be a formality where compliance with agreed specifications can be objectively established. Where that cannot be established, customer acceptance can be important to determining whether the service has transferred. The uncertainty over the fee still requires its separate assessment.
Review what the client is entitled to check or reject. Is it confirming an objective calculation using agreed data, or deciding whether the outcome meets a substantive condition? What unresolved matters could change the amount?
Keep correspondence showing the actual position. A client acknowledging receipt of a report is different from accepting its findings or agreeing to pay the success fee.
A Savings-Based Fee Needs a Supported Calculation
Consider a hypothetical consultancy entitled to 10% of qualifying procurement savings, subject to the contract’s performance and verification requirements. The project team calculates S$1 million of savings and proposes a S$100,000 fee.
The client disputes whether S$250,000 of the claimed savings relates to the consultancy’s work. It also questions whether certain reductions are recurring or merely the result of lower purchasing volumes. Those issues affect the basis of the calculation, not just the timing of payment.
Management should trace each category to the agreed methodology and supporting data. The disputed S$250,000 would represent S$25,000 of the fee calculation, but the remaining S$75,000 is not automatically recognisable. The performance, entitlement and variable consideration requirements still need to be assessed.
This example is illustrative, not a Kazuma client case. Its purpose is to show why identifying an undisputed-looking subtotal is only one step. The accounts need a supported conclusion about the amount that meets the relevant requirements.
Validate the Baseline and Measurement Period
A savings calculation depends heavily on its starting point. Different assumptions about historical prices, purchasing volumes or product mix can produce different outcomes from the same operational data.
Retain the agreed baseline and explain any adjustments. If the contract requires comparison with a specified prior period, the calculation should not quietly substitute a more favourable period. Where the parties agree a change, preserve that agreement.
Check that the measurement period is complete. A fee based on results sustained over several months may not be supported by a short period of promising performance. Forecasting the remaining months is different from documenting results already achieved.
Ensure the underlying data can be reproduced. A spreadsheet containing only final totals is harder to assess than a calculation linked to source reports, assumptions and clearly identified exclusions.
Distinguish Client Disagreement From Collection Risk
A client may reject the fee because it believes the target was not met. Another client may agree the amount but be unable to pay. These are different questions even if both result in an unpaid balance.
Establish whether the dispute concerns entitlement, measurement, performance or financial capacity. The accounting response should follow the cause. An amount not supported as revenue should not simply be recorded in full and addressed through a bad-debt allowance.
Retain evidence of the client’s position and management’s response. Avoid summarising a substantive disagreement as “payment delayed” in the receivables report.
This distinction also improves the next action. Negotiating a measurement difference requires different information from pursuing an acknowledged debt or assessing a customer’s ability to settle.
Do Not Let an Invoice Decide the Reporting
Issuing an invoice can formalise a request for payment, but it does not make an unsupported success fee earned. Management should assess the underlying position before relying on the invoice as evidence.
The reverse also needs care. A fee may require consideration before invoicing where the relevant accounting conditions have been met, but the classification of any resulting asset must be assessed. An amount still conditional on something other than the passage of time should not automatically be treated as an unconditional receivable.
Use clear descriptions in the reporting schedules. Distinguish invoiced fees, recognised amounts awaiting billing and potential fees that remain outside recognised revenue. A sales pipeline report should not become the ledger without review.
Where finance and the project team use different status definitions, reconcile them. “Project complete”, “fee calculated” and “client approved” should not be interchangeable labels.
Prepare a Financial Statements Audit Evidence File
For each material success fee, assemble the signed agreement, amendments, performance records, calculation and relevant client correspondence. Include management’s accounting assessment and the approval for the recorded entry.
The file should explain what was known at the reporting date. Identify unresolved questions and show how they affected the conclusion rather than presenting only documents that support the desired result.
Kazuma’s financial statements audit services provide independent examination of financial reporting. Management remains responsible for the revenue assessment and the completeness of the information supplied. The auditor’s role is not to negotiate the commercial fee on the consultancy’s behalf.
Raise significant arrangements early in the engagement. A material success fee with disputed measurement assumptions may require more discussion than routine fixed-fee assignments, especially where it has a substantial effect on annual profit.
Assess Information Received After Year-End
Client confirmation may arrive while the financial statements are being prepared. Its accounting effect depends on what it establishes about conditions at the reporting date.
A later confirmation might provide evidence that a condition had already been satisfied. Alternatively, the client may confirm a result achieved only after year-end or agree new commercial terms. Those situations should not be treated as identical.
Subsequent-events guidance distinguishes evidence about existing reporting-date conditions from conditions arising later. Management should assess the facts before adjusting the earlier period or concluding that disclosure is sufficient.
Keep the dated sequence of events. Preserve the original calculation, later confirmation and any revised amount so the reviewer can identify whether new evidence or a new event changed the position.
Review Fixed Fees and Success Fees Together
Many engagements combine a fixed retainer with an outcome-based payment. The contract may cover one overall service or several distinguishable promises. The fee headings alone do not settle the accounting analysis.
Explain how the arrangements relate. A fixed fee may cover work already performed, while the success fee remains uncertain. However, management should not assume that each billing component automatically corresponds to a separate performance obligation.
Ensure the calculation does not count the same remuneration twice. A contract may specify that retainers are credited against the eventual success fee, or that a cap applies to total consideration.
Reconcile cumulative billings, recognised revenue and amounts received over the engagement. This provides a clearer view than reviewing the success-fee invoice in isolation.
Keep Budgets and Incentives Separate From Recognition
A consulting firm may use expected success fees in its commercial forecast. That can be useful for planning if uncertainty is clearly identified, but a forecast does not establish the financial reporting treatment.
Show management the difference between pipeline, recognised revenue and cash collected. Each measure answers a different question. Combining them can make performance look stronger and liquidity more certain than the records support.
Review internal commission or bonus arrangements that refer to success fees. If staff incentives are calculated before client acceptance or collection, management needs to understand the terms and potential cash exposure separately from revenue recognition.
Pressure to meet a target should not determine an accounting judgement. A documented review by someone with appropriate authority helps the firm maintain consistency when a fee materially affects the reported result.
Use Past Outcomes to Improve Future Reviews
After a success fee is resolved, compare the final outcome with the earlier estimate. Examine whether differences arose from contract interpretation, incomplete data, client concessions or factors outside the consultancy’s control.
Use that information carefully. Experience with similar contracts can inform future assessments, but dissimilar projects should not be pooled simply to produce a reassuring historical success rate.
Update the process where recurring problems appear. Clearer measurement terms, earlier agreement on baselines and better communication between project teams and finance can reduce uncertainty before year-end.
Kazuma’s accounting support can help maintain the records underlying these reviews. The commercial team supplies the project facts, while consistent reporting makes changes in estimates and their reasons easier for management to understand.
Make the Revenue Conclusion Explainable
Success fees reward outcomes, but the accounts must reflect the contractual and reporting position rather than optimism about the project. Client confirmation is an important piece of evidence whose significance depends on what the agreement requires and what can otherwise be established.
Before finalising the accounts, review performance, validate the calculation and document the treatment of unresolved uncertainty. Keep invoice status, revenue recognition and cash collection distinct so each balance can be explained.
Speak with Kazuma about its financial statements audit and accounting services when preparing records for material success-fee arrangements. A clear evidence trail gives management a stronger basis for its conclusions and supports a more focused audit review.