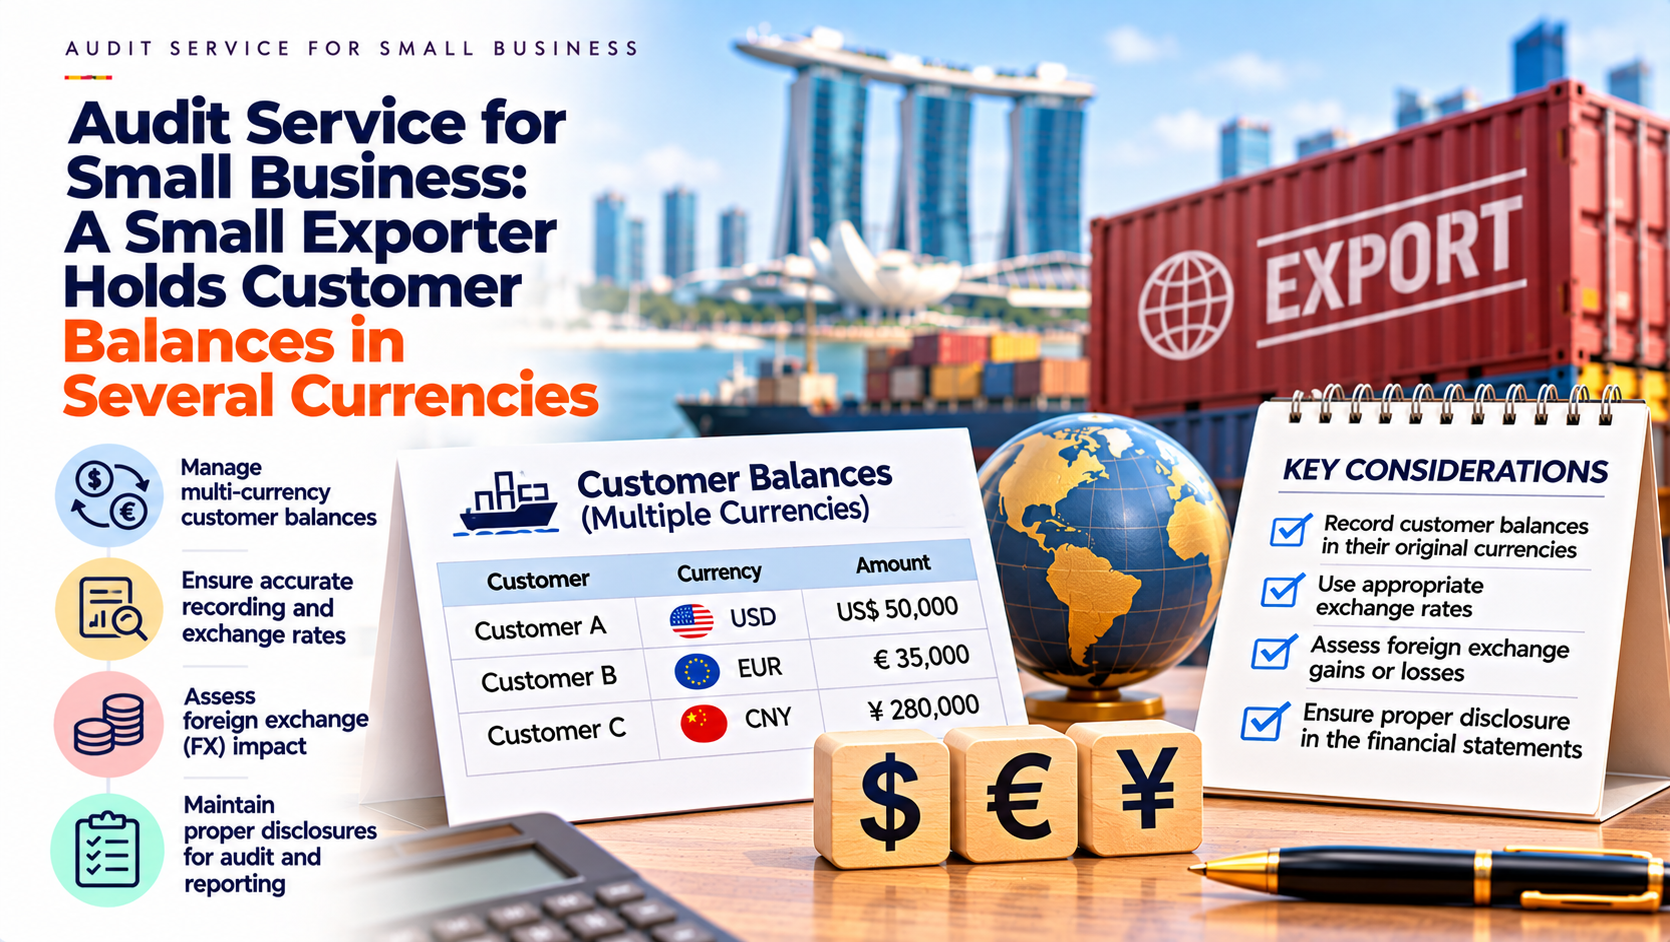
A small exporter may issue invoices in US dollars, Japanese yen and euros while paying many of its operating expenses in Singapore dollars. Customers settle their accounts at different times, sometimes through foreign-currency bank accounts and sometimes through automatic conversion. By year-end, the receivables report contains balances recorded using several exchange rates.
The total may look reasonable, but individual differences can be difficult to explain. A customer appears to have underpaid despite settling the full invoice. An outstanding balance remains at its original exchange rate. A bank charge is posted as an exchange loss, while a genuine customer deduction is cleared without investigation.
When choosing an audit service for small business, exporters should consider the records needed to support these transactions. Kazuma Public Accounting Corporation provides audit and accounting services in Singapore, including support for Japanese companies and parent-company reporting. Clear currency records help management explain both what customers owe and how those amounts appear in the accounts.
Establish the Company’s Functional Currency
The currency printed on an invoice is not necessarily the company’s functional currency. Functional currency reflects the primary economic environment in which the business operates. It should be assessed under the applicable reporting framework rather than selected solely because the company is incorporated in Singapore.
An exporter may have substantial overseas sales while its pricing, costs and financing arrangements point to a particular functional currency. A Japanese parent’s reporting currency also does not automatically determine the Singapore subsidiary’s functional currency.
Document the assessment and ensure the accounting system is configured consistently with it. Management should distinguish transaction currencies, functional currency and any presentation currency used for reporting. Otherwise, differences arising at separate stages can become mixed together and difficult to reconcile.
Retain the Original Currency Amount
Each customer balance should remain traceable to the currency and amount in the underlying invoice. A report containing only Singapore-dollar equivalents can make it difficult to establish whether the customer has paid the amount contractually due.
Maintain invoice-level records showing the original currency, original amount, receipts, credit adjustments and remaining balance. Link these records to the amount recognised in the functional-currency ledger. Where a customer trades in several currencies, keep those balances distinguishable.
This detail also improves communication. A customer can confirm that it owes US$25,000 without agreeing with the Singapore-dollar amount shown in the exporter’s internal report. The difference may concern translation rather than the underlying debt, so finance needs both views.
Record Transactions Using a Supported Rate
Foreign-currency transactions generally enter the functional-currency accounts using the exchange rate at the transaction date. The relevant date follows the accounting event being recognised; it should not automatically be replaced by the later payment date.
Finance should document the rate source and the policy applied. Where an average rate is used as an appropriate approximation, assess whether currency movements make that approximation unsuitable. A budget rate used to evaluate sales performance may serve a different purpose from a financial reporting rate.
Check system settings and manual entries for consistency. Errors can arise when one employee enters a direct rate while another uses its reciprocal, or when a spreadsheet applies a rate intended for a different currency pair. Clear labels and review procedures reduce these avoidable differences.
Review Outstanding Receivables at the Reporting Date
Ordinary foreign-currency trade receivables are monetary items. Under IAS 21, outstanding monetary items are generally translated using the closing rate at the reporting date. The resulting exchange differences usually affect profit or loss, subject to the relevant requirements and exceptions.
A receivable can therefore change in functional-currency value even though the customer owes exactly the same foreign-currency amount. This change should be distinguishable from a new sale, a customer credit or a collection problem.
Prepare a closing schedule showing the foreign-currency balances, rates applied and resulting functional-currency values. Reconcile it to the ledger and explain the adjustment. This gives management a clearer account of why reported receivables and exchange gains or losses have changed.
Follow an Invoice Through Year-End and Settlement
Consider a hypothetical exporter whose functional currency is Singapore dollars. It recognises a US$20,000 receivable when the exchange rate is S$1.35 for US$1. The initial functional-currency amount is S$27,000.
The invoice remains unpaid at year-end, when the closing rate is S$1.32 for US$1. Its translated amount becomes S$26,400, producing a S$600 exchange loss. The customer still owes US$20,000; the change concerns its Singapore-dollar equivalent.
Assume the customer subsequently pays in full when the rate is S$1.34 for US$1, and the receipt is immediately converted at that rate without fees. The company receives S$26,800 and recognises a S$400 exchange gain relative to the year-end carrying amount. The example excludes hedging and other complications, but shows why the settlement comparison must consider previous remeasurement.
Separate Bank Charges From Customer Shortfalls
The bank may credit less than the invoice amount because charges were deducted during the transfer. That difference should be investigated before finance treats it as an exchange loss or leaves the customer showing an unpaid balance.
Review the remittance advice and bank transaction details. Establish the amount the customer sent, the currency received and any deductions. The commercial terms may also determine who bears particular charges, so the appropriate customer balance depends on more than the net bank receipt.
Other differences may represent discounts, withholding, disputes or simple payment errors. Each requires its own assessment. Using a general exchange-difference account to clear every mismatch can conceal collection issues and distort the reported cost of currency movements.
Account for Partial Payments Carefully
A customer may settle an invoice through several transfers. Each receipt can occur at a different rate, while the remaining foreign-currency balance continues to require review. The system needs to preserve that sequence.
Match each receipt to the relevant invoice and quantity of foreign currency settled. Check how the system calculates exchange differences and carries forward the unpaid portion. Where the customer pays several invoices together, obtain an allocation rather than assigning the receipt arbitrarily.
At reporting dates, remeasure the remaining balance appropriately. Do not translate the original invoice amount again without deducting settled amounts. A simple invoice movement schedule can reveal errors that are difficult to identify from a total customer balance alone.
Keep Foreign-Currency Bank Balances Separate
Receiving a US-dollar invoice into a US-dollar bank account does not eliminate every exchange movement. The receivable has been settled, but the company now holds foreign-currency cash whose functional-currency value can continue to change.
Record settlement of the customer balance separately from later conversion of the bank funds. Otherwise, finance may incorrectly keep adjusting the customer account after the customer has paid or recognise the same exchange movement twice.
Reconcile foreign-currency bank accounts in both their original currency and the functional-currency ledger. Management should be able to distinguish exchange differences associated with collecting receivables from those arising while cash remains in the bank.
Assess Collection Risk Independently of Exchange Movements
A properly translated balance can still be difficult to collect. Exchange rates do not resolve customer insolvency, disputed deliveries or long-overdue invoices. Finance needs a separate assessment of recoverability under the applicable financial-instrument requirements.
Review ageing in the original currency and investigate overdue balances with the sales team. Subsequent receipts, payment commitments and dispute correspondence provide information about collection prospects. A favourable exchange movement should not distract management from worsening customer credit quality.
Keep exchange adjustments and credit-loss assessments separately traceable. Their effects may both change the reported receivable, but they address different uncertainties. Clear schedules make it easier to explain the final balance and avoid treating an exchange gain as evidence that the debt has become safer.
Reconcile Reports Sent to Japan Headquarters
A Singapore exporter with a Japanese parent may submit reports in yen while maintaining its underlying books in another functional currency. The group reporting process can therefore add another layer of currency translation.
Clarify the purpose and instructions for each reporting package. Reconcile the local ledger to the submitted figures, identifying reporting adjustments and translation steps. Avoid changing local transaction records merely to force agreement with a headquarters presentation.
Kazuma’s services include parent-company reporting and consolidation package support for Japanese clients. That positioning is relevant where local finance and headquarters need a shared explanation of currency differences. Management should retain a clear distinction between local transaction accounting and translation for group reporting.
Prepare Supporting Records for the Audit
An audit service for small business still requires evidence appropriate to the company’s transactions. A small number of employees or customers does not remove the complexity created by several currencies and payment channels.
Prepare the receivables ledger, invoices, relevant sales and delivery records, remittance advice and bank statements. Retain the exchange-rate sources and the closing remeasurement calculation. Explain manual adjustments and identify balances subject to dispute or unusual settlement arrangements.
Auditors may seek customer confirmations or examine subsequent receipts, depending on the circumstances. A customer confirmation should clearly identify the currency being confirmed. Management remains responsible for the records and accounting conclusions, while the auditor independently evaluates the supporting evidence.
Avoid Using Budget Rates to Explain Away Accounting Differences
Sales teams may use fixed planning rates to compare margins across periods. Such information can be useful for evaluating commercial performance, but it should be labelled clearly and reconciled to the financial accounts.
A budget-rate profit report and a financial statement report may show different outcomes without either being a simple arithmetic error. The problem arises when management treats them as interchangeable or posts adjustments solely to make them agree.
Explain the role of each report. Show how currency movements affect reported results and distinguish those movements from changes in selling prices, volumes or operating costs. This helps management assess business performance without losing sight of the actual financial position.
Use Currency Schedules to Improve Cash Planning
The receivables schedule can also support a more realistic cash forecast. Expected receipts should identify currency, timing and the assumptions used when estimating funds available for operating payments.
Consider whether receipts will remain in foreign-currency accounts or be converted. Match the forecast with commitments in the same currencies where appropriate, while recognising that collection dates may differ from payment dates. A forecast should not assume perfect timing simply because currency totals appear to offset.
If management uses forward contracts or other arrangements to manage exposure, keep their documentation and accounting assessment separate from the basic customer reconciliation. Their existence should not lead finance to translate every receivable automatically at a contracted future rate.
Make Each Currency Balance Explainable
A small exporter should be able to show what each customer owes, how the functional-currency amount was calculated and what happened when payment arrived. Consistent records make exchange differences easier to distinguish from bank charges, customer deductions and genuine credit concerns.
Regular reconciliation also reduces the work left for year-end. Reviewing rates, allocations and overdue balances throughout the year gives management more reliable information for collection and cash decisions, while making the audit evidence easier to assemble.
When considering an audit service for small business, discuss the company’s currencies, banking arrangements and reporting requirements with Kazuma PAC. Bring the customer schedules and exchange calculations so that the engagement’s information needs can be understood early, including any coordination required with headquarters in Japan.