The Distributor’s Exclusive Deal Comes With a Minimum Purchase Commitment
An overseas appliance brand offers a Singapore distributor exclusive rights to its product range. The proposal promises a stronger market position, fewer direct competitors carrying the same products and an opportunity to build recurring retailer orders. There is one significant condition: the distributor must purchase an agreed minimum quantity every year.
For the owner, the attraction is understandable. Exclusivity could give the business something competitors cannot easily offer. However, the supplier’s purchase target becomes the distributor’s stock, funding and sales challenge. A product can offer an attractive margin on paper while tying up more cash than the business can comfortably support.
Kazuma provides accounting support that helps businesses maintain reliable financial records. For a distributor evaluating an exclusive arrangement, those records provide a foundation for testing demand, stock requirements and payment commitments. Before accepting the deal, management needs to understand what it must buy, when it must pay and how much customer demand is supported by evidence.
Define What the Exclusive Rights Actually Cover
“Exclusive distributor” can describe arrangements with very different commercial value. The rights may cover a territory, particular products or selected sales channels. The supplier may retain direct sales to major customers, operate its own online store or exclude future product launches from the agreement.
Clarify these boundaries before forecasting sales. A distributor expecting access to the entire local market could overestimate demand if major accounts remain with the supplier. Similarly, an exclusive right to sell an existing range may be less valuable if a replacement range falls outside the arrangement.
Management should identify the customer groups and channels it can realistically serve under the proposed terms. Contractual scope and enforceability need appropriate legal review, while the financial forecast should reflect the agreed commercial position. A broad description in a presentation should not become an assumption of unrestricted market access.
Translate the Minimum Into Specific Products and Dates
An annual purchase value is not enough to build a useful forecast. Establish whether the commitment is measured by units, invoice value, shipments or payments. Determine whether it applies across the range or requires minimum quantities of individual models.
Product mix can change the exposure substantially. A commitment that allows the distributor to concentrate on proven sellers differs from one requiring equal quantities of compact, premium and specialist appliances. The headline purchase amount may be identical, but the likely pace of sales will not be.
Timing matters too. An annual target delivered in flexible batches gives management a different funding profile from a large shipment required at launch. Record ordering deadlines, deposit dates, shipment schedules and balance-payment dates. These details turn a commercial promise into a calendar of obligations the business can assess.
Separate Confirmed Orders From Expressions of Interest
Retailer enthusiasm is useful information, but it is not the same as an order. A buyer may like the range while still requiring product testing, listing approval, promotional support or a trial period before committing to stock.
Build the demand forecast in layers. Identify confirmed orders, repeat demand supported by comparable sales, active negotiations and speculative opportunities. Record expected quantities and timing, along with any customer cancellation or return rights that affect the reliability of those orders.
Avoid treating the supplier’s regional sales figures as proof of local demand. Pricing, retail channels and competing products may differ. The distributor needs evidence relevant to the customers it intends to serve.
Where possible, test the range before accepting a large commitment. A limited launch can reveal which models attract repeat orders, how much support retailers need and whether the expected selling price holds after negotiation. Early information has more value when the purchase schedule leaves room to respond to it.
A Profitable Sales Forecast Can Still Leave Cash in Stock
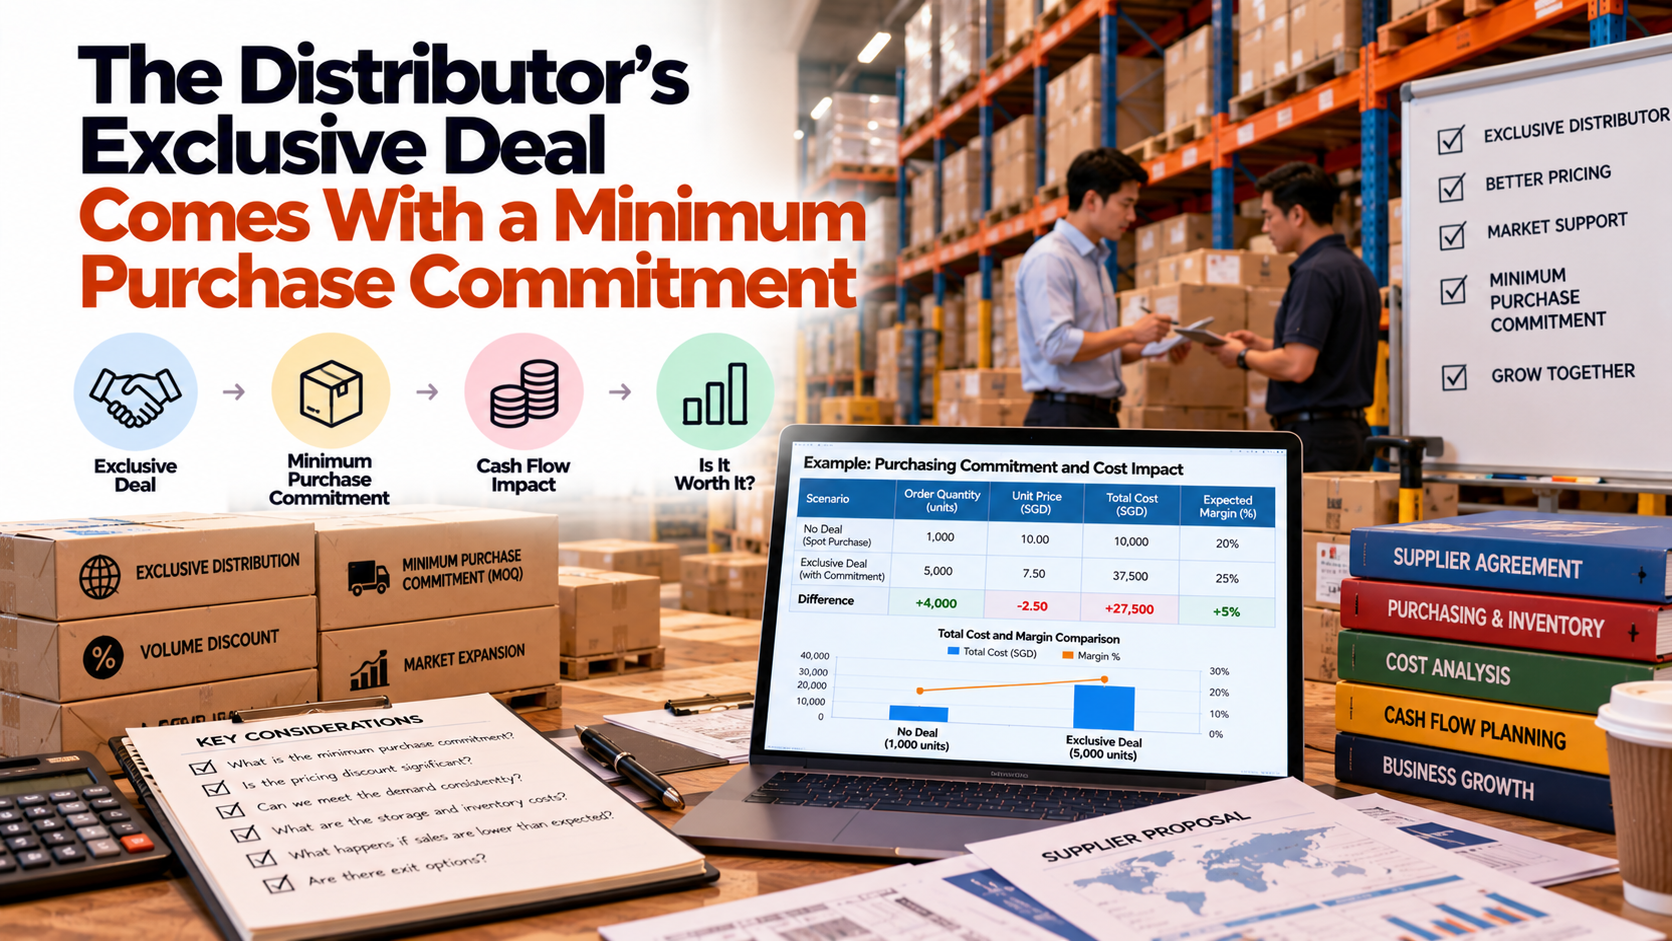
Consider a hypothetical distributor that commits to buying 1,200 appliances at S$100 each, creating a S$120,000 purchase commitment. It expects to sell them to retailers at S$145 each. If every unit sells at that price, the difference between sales and purchase cost would be S$54,000 before freight, selling costs and other expenses.
Now assume only 800 units sell during the first year. Revenue would be S$116,000, with S$80,000 in purchase cost attached to those units. The resulting S$36,000 difference is before the other costs of operating the arrangement, while 400 units with an original purchase cost of S$40,000 remain unsold.
If the full S$120,000 supplier bill has been paid and all S$116,000 of customer invoices have been collected, product cash receipts are still S$4,000 below product purchase payments. Freight, marketing and other expenditure create further cash demands. There is no contradiction: the trading result and the cash position are measuring different things.
The remaining stock may still sell, but management must fund it in the meantime. Its future selling price and condition also require review. The example is illustrative, not a Kazuma client case, and shows why the minimum purchase commitment needs a cash forecast alongside a sales forecast.
Calculate What Remains After Supporting the Brand
The gap between purchase price and selling price is only the starting point. Introducing a new appliance range may require freight, storage, retailer demonstrations, samples, sales commissions and promotional contributions. Some retailers may also request listing support or extended payment terms.
After-sales responsibilities deserve their own estimate. Establish who handles faulty products, replacement units, spare parts and customer enquiries. A supplier’s promise to reimburse certain costs may depend on approval procedures or supporting documentation, so the distributor should understand how the arrangement works in practice.
Separate launch expenditure from recurring costs. A one-time demonstration display differs from a continuing obligation to fund retailer promotions. Both affect the decision, but they should not be spread or repeated in the forecast without a clear basis.
Review the expected contribution by model and channel. A premium appliance may carry an attractive selling price yet require more demonstration and service support. A simpler model may generate less per unit but sell with fewer demands on the team.
Map the Largest Funding Gap
A year-end cash balance can conceal the point at which the distributor needs the most funding. The supplier may require a deposit before production and the balance before shipment, while retailers pay only after delivery and invoice approval.
Prepare a monthly cash schedule, moving to weekly detail around major shipments if necessary. Include supplier payments, freight, launch spending and the expected collection dates for customer invoices. Identify the lowest cash point and compare it with funding that is genuinely available.
Test slower collections as well as slower sales. Even when orders arrive as expected, delayed retailer payments can extend the funding gap. A plan that works only if every customer pays on the earliest possible date leaves little room for normal variation.
Keep the rest of the business in the forecast. Existing suppliers, payroll and operating expenses still require payment. The exclusive range should not appear affordable simply because the model assumes all available cash can be devoted to it.
Understand What Happens If the Target Is Missed
The minimum purchase requirement may have different consequences depending on the contract. Falling short could affect exclusivity, future pricing, renewal or other obligations. Management should establish the actual position rather than assume there is either no consequence or an automatic requirement to buy every missing unit.
Have the relevant terms reviewed and translate the confirmed consequences into financial scenarios. Include any notice periods, review dates and opportunities to adjust the target by agreement. The purpose is to understand the exposure while there is still time to negotiate.
Pay attention to the measurement period. A contract year that begins partway through the calendar year may not align with management’s normal reporting cycle. Someone should be responsible for tracking progress against the contractual dates, not merely reviewing annual sales after the deadline has passed.
Plan for Slow Models and Product Changes
A range can achieve healthy overall sales while leaving certain models behind. Those units occupy storage, absorb cash and may become harder to sell when the supplier launches an updated version. Reviewing only total purchases and total sales can hide the imbalance.
Track stock and customer demand by model. Record how long units have been held, upcoming replacement launches and the discounts needed to move older products. Early visibility allows management to discuss order changes before another shipment repeats the same problem.
Clarify whether the supplier offers exchanges, returns or price protection, and under what conditions. These protections should be supported by the agreement rather than assumed from informal assurances. A limited exchange window may be useful only if the distributor identifies the slow stock in time.
Avoid making a clearance forecast depend on selling every remaining unit at its original planned price. Model a realistic alternative, including the effect of discounts and the time required to collect the proceeds.
Compare the Deal With Other Uses of the Same Resources
The exclusive range will use more than purchasing funds. It may occupy warehouse space, sales visits and management attention that could support existing products. The relevant comparison includes credible opportunities the business would give up.
Focus on future revenue and costs that change because of the decision. Existing expenses that remain unchanged should not be treated as new spending, while additional warehouse space or a new sales role clearly needs consideration. Where a constrained resource would otherwise earn contribution, that alternative matters.
Do not assume that the existing sales team can absorb the launch without affecting anything else. Ask which accounts or activities will receive less attention and whether that trade-off is acceptable. A forecast that includes all the new sales while preserving every existing sale may be too optimistic.
Negotiate Terms Around the Main Exposure
Once the financial pressure points are clear, negotiation can become more specific. A distributor facing uncertain demand may seek a smaller initial commitment with a later review. One facing a timing problem may prioritise staged deliveries or a payment schedule that better matches collections.
Product flexibility may be more valuable than a slightly lower unit price. The ability to adjust the model mix could reduce slow stock, while clear arrangements for discontinued products could protect against a launch becoming outdated too quickly.
Supplier support should also be defined. Marketing contributions, training and service arrangements are easier to include in a forecast when responsibilities and approval processes are clear. An unspecified promise of support should not carry the same weight as an agreed commitment.
These are commercial options to discuss, not protections that automatically apply. Management should update the forecast using the final terms before approval, particularly if negotiations change the purchase target or payment schedule.
Give the Agreement a Monthly Financial Review
After signing, monitor purchases, sales to retailers, customer collections and closing stock against the original plan. Where reliable information is available, retailer sell-through can help distinguish genuine consumer demand from stock that has merely moved into another warehouse.
Kazuma’s accounting support can help provide consistent records for this review. Management can then examine why cash requirements or margins differ from expectations and decide what needs attention. Accurate reporting is most useful when it reaches the decision-makers before the next purchase deadline.
Assign responsibility for the assumptions that matter. The sales team should update expected orders, purchasing should track commitments, and finance should reconcile payments and collections. A shared forecast reduces the risk of each department relying on a different version of the deal.
Set review triggers in advance, such as slower sales of a key model or a funding gap above the agreed limit. Those triggers should prompt a commercial review while options remain available, rather than simply explain an unfavourable result later.
Make Exclusivity Earn Its Commitment
An exclusive arrangement can give a distributor a useful position in the market, but the rights need to justify the obligations attached to them. The strongest case connects realistic demand with a workable purchase schedule, sufficient funding and an acceptable downside if sales develop more slowly.
Before committing, bring the product forecast, contract terms and cash schedule into one decision. Identify which assumptions are supported, which still need testing and which terms would make the opportunity manageable. The objective is to understand how the deal will perform beyond the launch announcement.
Speak with Kazuma about its accounting support if the business needs clearer financial information behind its expansion decisions. Reliable records help management see whether an exclusive range is building sustainable earnings or simply increasing the amount of cash committed to stock.