The carpentry subcontractor has received a deposit, the electrician has submitted a progress claim, and the flooring contractor wants another payment before installation begins. Meanwhile, the client’s renovation is still several weeks away from completion. As year-end approaches, the interior design firm’s accounts show money leaving the bank, but the project records do not yet explain exactly what those payments represent.
For the business owner, this creates more than a bookkeeping question. Some payments may secure future work, others may settle work already performed, and certain amounts may relate to materials awaiting delivery. Treating everything as an expense, or leaving everything under project advances, can obscure the financial position.
Kazuma provides statutory audit and accounting support in Singapore. For interior design firms considering Singapore audit services, a useful starting point is connecting subcontractor payments with contracts, progress records and outstanding obligations. That connection helps management explain what has been received, what remains to be delivered and which balances require further review.
A Payment Confirms That Cash Moved, Not That Work Was Completed
Subcontractors request payment at different stages for different reasons. A carpenter may need an advance to purchase boards and fittings, while an electrician may bill after completing concealed wiring. A flooring contractor might request payment before reserving a particular material batch. These arrangements can all be commercially reasonable, but they represent different stages of performance.
The payment description in the bank statement rarely captures those distinctions. An entry labelled “Project A contractor payment” tells finance little about whether it relates to future work, an agreed progress claim or an outstanding balance from an earlier stage. Even a supplier invoice may describe a payment milestone without establishing what was actually delivered.
The first task is therefore to identify the purpose of each material payment. Finance should be able to connect it to the subcontract, the relevant claim and the project manager’s assessment. Where the records disagree, that difference needs investigation before the balance is classified.
Separate Advances From Work Already Received
An advance for future subcontractor services is different from a payment for services already received. A recoverable advance may remain an asset until the relevant goods or services are supplied. Once performance occurs, the accounting needs to reflect what has been received and the applicable reporting requirements.
An unfinished customer project does not mean every related payment qualifies as an asset. Under the relevant contract-cost guidance, capitalisation depends on specific criteria, including a connection to future performance and expected recovery. Costs relating to work already performed cannot simply be deferred to protect the project’s reported margin.
Avoid using a single “work in progress” account as a holding area for every uncertain item. Materials, subcontractor advances, costs incurred and customer contract balances may require different assessments. Clear descriptions help finance identify the issue rather than allowing an account label to stand in for an accounting conclusion.
Build a Payment Schedule That Explains Each Balance
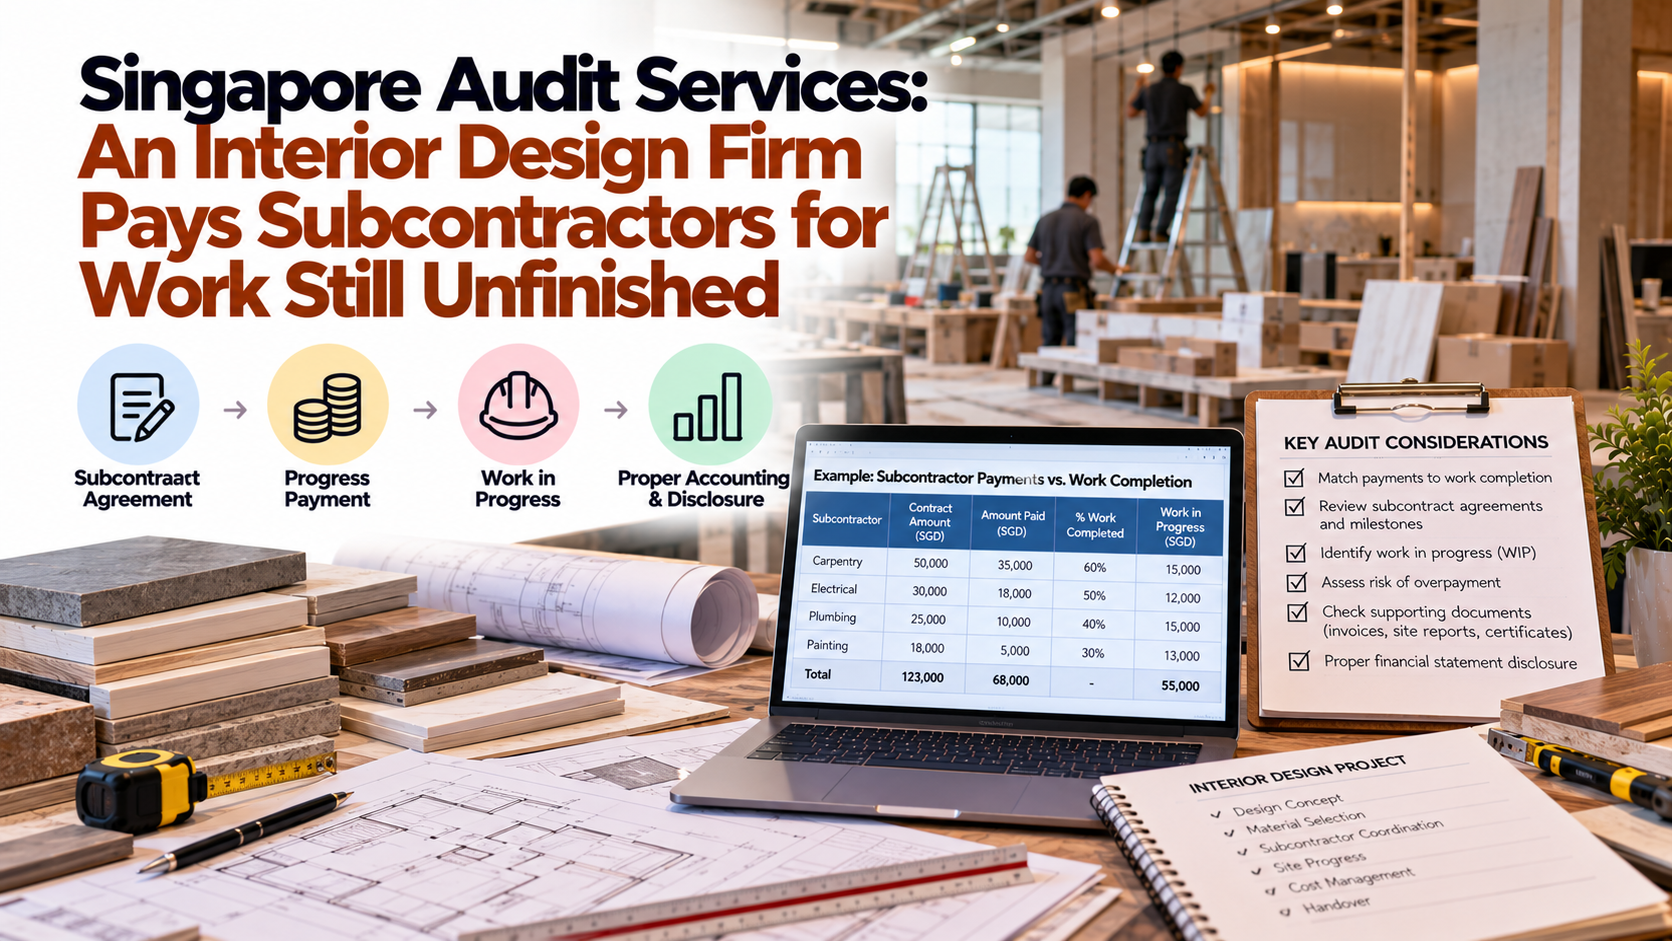
A useful subcontractor schedule should show the project reference, subcontract value, approved variations, payments made and how advances have been applied against subsequent claims. It should also identify claims received, amounts assessed as relating to completed work and unresolved differences.
This prevents a common operational problem: paying an initial deposit and later settling a progress invoice without deducting the agreed advance. If the payment history and claims register sit in separate files, the duplicate settlement may not be obvious until the subcontractor’s final account is reviewed.
Reconcile the schedule to the ledger regularly. A difference may arise from an incorrectly assigned project code, a payment covering multiple jobs or a credit note that has not reached finance. Investigating these matters while the project is active is generally easier than reconstructing them after the site team has moved on.
What a Year-End Payment Might Represent
Consider a hypothetical interior design firm that pays S$60,000 under a S$100,000 carpentry subcontract before 31 December. The project manager’s supported assessment shows S$35,000 of work received by that date. Assume the contract and payment records establish that the remaining S$25,000 is an advance for future work, with no separate materials transferred and no recoverability concern.
On those assumptions, the entire S$60,000 should not automatically be treated as a current-period expense. Equally, keeping the full amount as an advance would overlook the work already received. The S$35,000 requires the appropriate project-cost treatment, while the remaining S$25,000 needs to remain identifiable as an advance.
The figures illustrate the reconciliation process, not a universal accounting entry. Different contractual terms, materials arrangements or performance facts could change the outcome. The important point is that the payment total must be explained using evidence rather than treated as a measure of completion.
Progress Claims Need Supporting Detail
A subcontractor’s claim is evidence of what the subcontractor is requesting, but it is not necessarily conclusive evidence of work performed. The claim may include materials not yet delivered, work awaiting inspection or a variation that management has not agreed.
Ask the project manager to document the basis for reviewing significant claims. That might include completed quantities, installation records, dated photographs, inspection notes and a comparison with the agreed scope. The support should relate to the reporting date, rather than showing only that the work was eventually completed.
A broad statement such as “carpentry approximately 70% complete” may be insufficient where a substantial balance depends on it. Explain what has been completed, what remains outstanding and how the assessment was calculated. Supporting detail makes the judgement understandable to someone who was not present on site.
Materials at a Subcontractor’s Workshop Need Separate Attention
An interior design firm may pay for customised cabinets or fittings while they remain at the subcontractor’s premises. Physical location alone does not settle whether those items belong in the firm’s accounts. The contract, identification of the goods and evidence concerning control need examination.
Keep records showing which materials relate to the project, whether they have been separately identified and what the agreement says about ownership, delivery and substitution. An invoice stating “materials purchased” does not necessarily establish that specific goods have been transferred to the firm.
Management should also understand the practical exposure. If the subcontractor stops operating, can the firm identify and obtain the materials it has paid for? Are they usable for the intended project, and has the client changed the design? These questions help identify balances that need more than a routine confirmation of payment.
Look for Work Received Before the Invoice Arrives
Year-end review should consider the opposite situation too: work completed before year-end but invoiced afterwards. If finance relies only on invoices already received, the accounts may omit obligations for services received during the reporting period.
Ask project managers to identify completed subcontractor work for which claims are outstanding. Review subsequent invoices against the dates and nature of the underlying work. A January invoice may relate to December performance, January performance or a combination of both.
Keep an explanation of any estimate used and reconcile it when the final claim arrives. This reduces the risk of both omission and double-counting. The later invoice should be matched against the existing accrual where appropriate, rather than automatically recorded as an entirely new project cost.
Do Not Use Subcontractor Payments as a Shortcut for Revenue
An interior design firm may collect a customer deposit, make subcontractor advances and issue progress invoices on separate schedules. Those cash movements and billing milestones do not necessarily measure the firm’s performance under its customer contract.
Revenue recognition requires an assessment of the contractual promises and when they are satisfied. Where recognition over time is appropriate, the measure of progress must reflect performance. Paying a substantial advance to a subcontractor does not, by itself, demonstrate equivalent progress on the customer project.
This matters when management monitors project margins. Recording customer revenue using one unsupported percentage and subcontractor costs using another can create a misleading result. Review the customer contract and subcontractor records together while preserving the distinct accounting assessment required for each.
Keep Variations, Retentions and Disputes Visible
Renovation projects often change after work begins. A client may request additional cabinets, different lighting or a revised layout, and the subcontractor may submit a corresponding variation. The customer’s approval and the subcontractor’s claim are related commercially, but they are separate matters to document.
Maintain a variation register showing the requested change, supporting quotation, approval status and work performed. A subcontractor cost should not be ignored simply because recovery from the customer remains uncertain. Conversely, a proposed charge does not become an agreed obligation merely because it appears on a claim.
Retentions also need separate tracking. Amounts withheld under contractual terms may relate to work already performed, so the absence of payment does not automatically remove the associated obligation. Record the reason for withholding, the release conditions and any dispute requiring further assessment.
The aim is to avoid concealing uncertainty within a net project balance. Management should be able to identify an unpaid claim, a recoverable advance and a disputed variation individually, even when they all relate to the same subcontractor.
Review Whether Old Advances Will Be Recovered
An advance can remain on the ledger long after the original completion date has passed. The subcontractor may have delayed the work, the customer may have suspended the project, or management may have appointed a replacement contractor. An old payment description does not establish that the balance remains recoverable.
Review aged advances against current project status. Obtain updated correspondence, revised delivery commitments and evidence of subsequent work or repayment. If the original arrangement has broken down, assess the rights and realistic recovery prospects instead of carrying the balance forward without explanation.
Replacement costs should be recorded separately from the original advance. Paying another contractor to finish the work does not demonstrate that the first payment will be recovered. Management needs to see the total financial exposure, including any remaining claim against the original subcontractor.
Prepare Project Evidence for Singapore Audit Services
A practical audit file should allow a reviewer to follow a significant balance from the ledger to the project schedule and then to supporting documents. Relevant records may include signed subcontracts, approved variations, payment details, progress assessments and correspondence about outstanding work.
Explain unusual items before they become unexplained differences during the audit. If a project manager’s estimate differs from the subcontractor’s claim, record the reason. If goods remain off-site or an advance is overdue, identify the evidence supporting management’s conclusion.
Kazuma’s audit services provide independent scrutiny of financial reporting. Management remains responsible for maintaining records and making the accounting assessments. A financial statement audit also does not replace the technical assessment of construction quality or site safety; those questions require the appropriate operational expertise.
Well-organised records make the financial review more focused. They allow discussions to address the substance of a balance rather than spend time identifying which project a payment belongs to or locating the latest version of an agreement.
Use the Review to Improve Payment Decisions
The year-end exercise can reveal weaknesses worth addressing during the next project. Repeated unapplied advances, unsupported progress approvals or missing variation records indicate that the payment process needs clearer responsibilities.
Agree who checks the subcontract terms, who verifies progress and who approves payment. Finance should receive enough information to record the transaction correctly, while project managers should know which outstanding balances require follow-up. Significant exceptions need a responsible person and a target date.
The same information can improve cash planning. A project may appear adequately funded until management compares remaining customer collections with unpaid claims, future subcontractor commitments and potential rectification costs. Keeping those amounts visible helps the owner understand the cash still needed to complete the job.
Make Every Subcontractor Balance Explainable
Interior design firms frequently pay before all work is complete. The reporting challenge is to distinguish the reasons behind those payments and assess what they represent at year-end. A bank transfer, invoice date or unfinished site cannot answer that question alone.
Before closing the accounts, reconcile advances, review work received, investigate outstanding claims and assess recoverability. Connect each material balance to the contract and project evidence that support it. This gives management a clearer view of both the financial statements and the commitments still ahead.
For interior design businesses seeking Singapore audit services, speak with Kazuma about its audit support and the records relevant to your circumstances. Clear subcontractor schedules and documented project assessments provide a stronger starting point for explaining the year-end position.