Your recruitment firm invoices a client S$50,000 for temporary staffing. Most of that amount covers the people performing the work, while the balance represents what your business retains. When preparing the accounts, should you record S$50,000 as revenue and the staffing costs separately, or recognise only your fee?
The answer depends on what your firm has promised to provide and its role in delivering that service. Collecting the full amount does not automatically make all of it revenue. Equally, describing part of an invoice as a salary reimbursement does not automatically mean that amount should be excluded.
For recruitment businesses seeking audit services Singapore companies rely on, this is a practical financial reporting issue. The treatment can materially change reported turnover and margin percentages, even where the cash collected and the amount retained are identical. Understanding the arrangement before year-end makes the accounting easier to support.
Start With What the Client Is Buying
Temporary staffing arrangements can look similar on an invoice while operating differently. One firm may undertake to provide suitable personnel throughout an assignment. Another may introduce candidates whom the client employs directly. A third may administer payments for an arrangement established by other parties.
Begin by identifying the service promised to the client. Is your firm responsible for supplying staffing capacity, arranging access to another provider’s service, or providing a separate recruitment or payroll administration service?
Under IFRS 15 and the corresponding full Singapore revenue standards, the principal-versus-agent assessment considers whether the entity controls the specified service before it is transferred to the customer. A principal reports the relevant revenue gross; an agent reports its fee or commission.
This assessment concerns control of the service or the right to that service. It does not mean ownership of the individuals carrying out the work. Keep that distinction clear when discussing the accounting with operational staff.
Read the Client Agreement Alongside the Other Contracts
The client agreement is an important starting point, but it may not explain the entire arrangement. Employment agreements, contracts with another staffing provider and assignment schedules may clarify who undertakes the work and who is responsible for supplying it.
Read those documents together. Establish which entity the client can hold responsible if the agreed staffing service is not delivered. Check whether your firm is committed to providing replacements, meeting staffing levels or addressing unsuitable performance.
Also identify what your firm can direct under the arrangement. For example, can it assign suitable personnel to the engagement, substitute individuals within the agreed requirements or obtain and direct services from another provider?
Record the relevant clauses and explain how they fit together. A short accounting memo supported by specific contractual terms is more useful than a broad statement that the company has always treated temporary staffing invoices as revenue.
Look Beyond Who Gives Daily Instructions
The client will often direct day-to-day activities at its premises. It may set shift times, explain tasks and approve attendance. Those facts help describe the service, but they do not automatically establish that the recruitment firm is only an agent.
Consider a firm that promises to supply a stated number of suitable workers for a defined period. The client may supervise their daily tasks while the firm remains responsible for fulfilling its staffing commitment. That differs from a business whose promise is limited to arranging an introduction.
The accounting analysis should reflect the full arrangement rather than selecting one operational feature. Ask what would happen if someone did not attend, the required skills were missing or the assignment needed a replacement.
Use actual examples where available. Emails about replacement requests and records of how they were resolved may help explain whether the written responsibilities reflect what happens in practice.
Assess the Relevant Indicators Together
The revenue standard identifies indicators that can support the control assessment, including primary responsibility for fulfilment, inventory risk and discretion over pricing. Their relevance varies with the service and contractual circumstances; they are not a points-based checklist.
For staffing services, explain the commercial commitments in concrete terms. Does the firm commit to obtaining service capacity before securing a corresponding client assignment? Can it set the client charge, or is it collecting amounts fixed by another provider?
Avoid treating a markup as conclusive. An agent can earn a variable fee, and a principal can work under tightly negotiated pricing. The amount retained does not by itself establish the nature of the promise.
Similarly, a payment obligation or exposure to late-paying clients does not settle the control question alone. Those facts may be important to understanding the business, but management needs a reasoned conclusion based on the arrangement as a whole.
Compare Two Simplified Arrangements
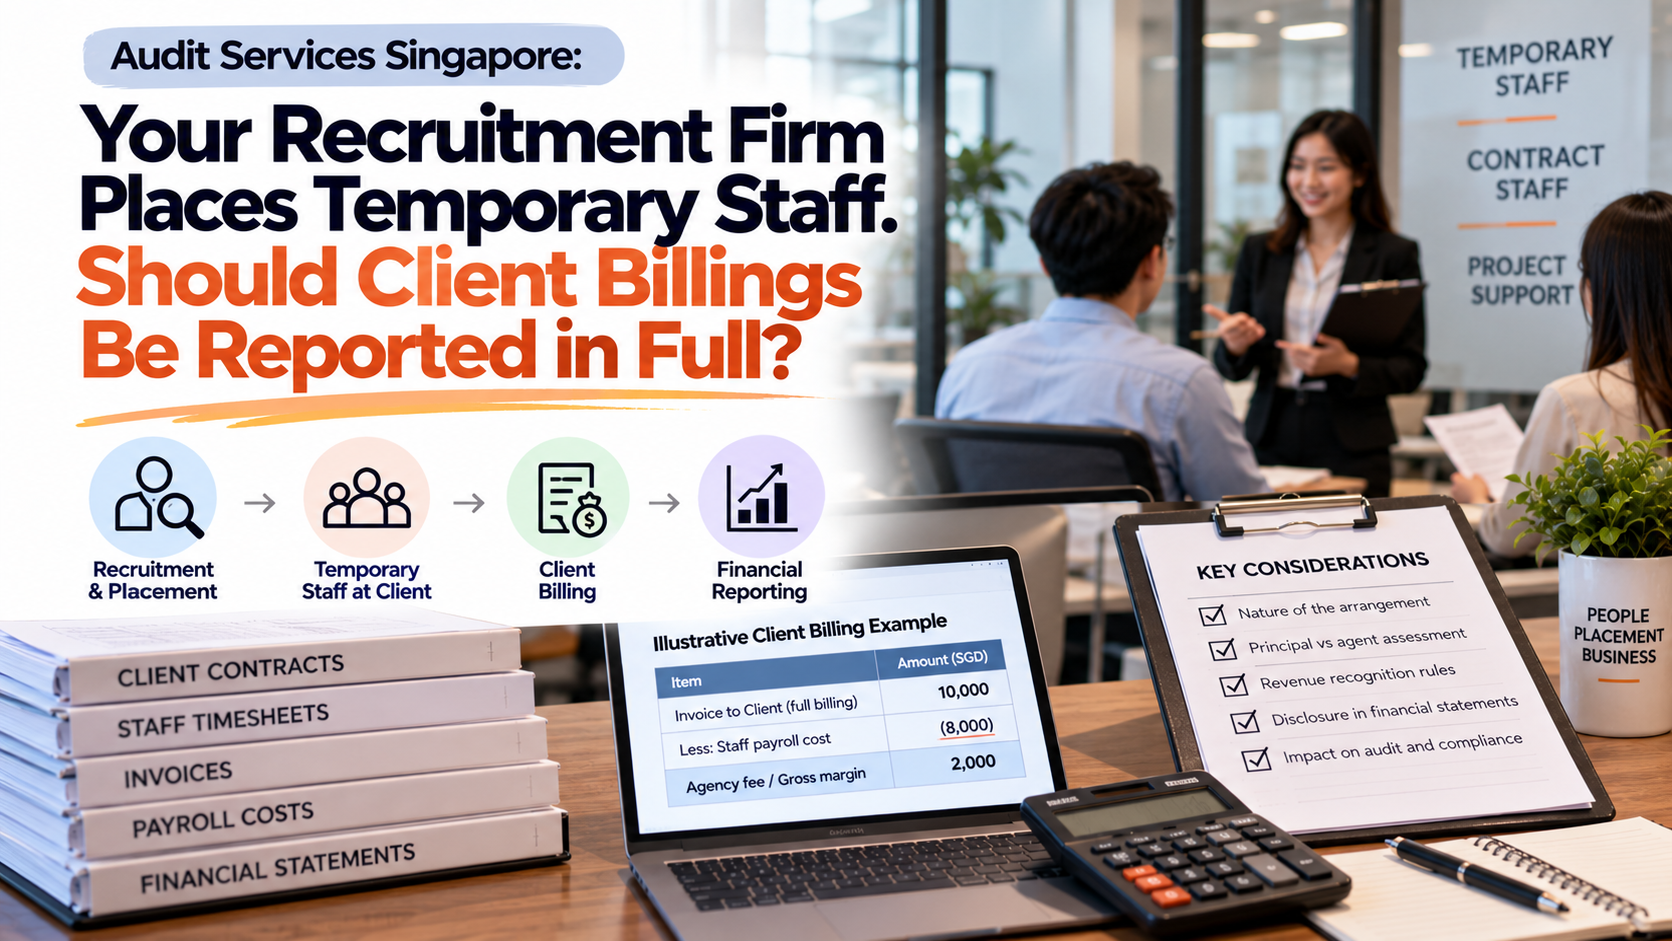
Consider two hypothetical businesses handling S$50,000 of client payments in a month. Assume the first business has assessed its contracts and concluded that it is the principal for the staffing service. It earns S$50,000 and incurs S$42,000 in the associated staffing costs.
On that simplified basis, it reports S$50,000 of revenue and S$42,000 of related costs, leaving S$8,000 before other operating expenses. The example assumes the costs are complete for the comparison and ignores taxes, adjustments and other services.
Now assume the second business has a different arrangement. It acts as an agent for a staffing provider, collects S$50,000 and must remit S$42,000 to that provider. Its agreed fee is S$8,000.
The second business reports S$8,000 of revenue for its arranging service. The S$42,000 collected for the provider is not its own staffing expense in this illustration.
Both businesses retain S$8,000 before other costs, but they report different revenue because their contractual roles differ. The treatment is a conclusion about the facts, rather than a choice between two presentations that management finds equally convenient.
Do Not Let Invoice Descriptions Decide the Accounting
Invoices often divide charges into wages, statutory employment costs, administration and markup. That breakdown may help the client understand the price, but it does not independently determine which amounts are revenue.
For example, a firm providing a staffing service might calculate its price by adding a margin to its employment costs. Calling those underlying costs “reimbursements” does not remove the need to assess the service it controls and provides.
Conversely, a business arranging another provider’s service might issue one invoice covering the full collection. The single invoice does not turn money collected for that provider into the arranger’s own revenue.
Ask finance to map invoice categories to the accounting conclusion. Where the invoice template uses terminology that could be misunderstood, retain an explanation of the commercial purpose of each line. This helps prevent bookkeeping rules from being driven solely by labels.
Consider Whether Different Services Need Different Conclusions
A recruitment firm may provide permanent placements, temporary staffing and payroll administration. It should not assume that one gross-or-net conclusion applies to every service merely because the same company invoices them.
Some client agreements may also contain several promises. A placement fee and an ongoing administration charge could relate to different activities. Management needs to identify the relevant services before deciding how their revenue is presented.
Prepare a contract register that groups genuinely similar arrangements. Record the service type, key responsibilities and the accounting approach, with a reference to the supporting assessment. Identify exceptions rather than forcing unusual contracts into the most common category.
This makes the review more manageable. Finance can apply a supported approach consistently to comparable contracts while referring new or changed arrangements for further analysis.
Keep Revenue Timing Separate From Gross-or-Net Presentation
Determining whether revenue is gross or net does not answer when it should be recognised. Your firm still needs to assess when the promised service is performed and what amount it is entitled to recognise.
For operational purposes, maintain a clear connection between assignments, approved hours, agreed rates and invoices. Investigate unapproved timesheets and disputed charges rather than assuming every system-generated amount is final.
At year-end, identify services performed but not yet billed, as well as billings relating to future periods. The appropriate accounting treatment depends on the contractual rights and applicable revenue requirements, not simply the invoice date.
Keep these questions distinct in the review. A correct principal-versus-agent conclusion can still be accompanied by an error in the reporting period or amount. Separating the issues makes discrepancies easier to explain and resolve.
Prepare Evidence That Explains the Business to the Auditor
A useful audit file should bring together representative contracts, the accounting assessment and supporting transaction records. Include the documents needed to understand each significant type of staffing arrangement.
For selected transactions, make it possible to follow the assignment through attendance approval, client billing, payments to the relevant parties and any subsequent adjustments. Explain significant differences between those records.
Where another provider is involved, identify that provider’s role and the amounts payable to it. Where the firm employs the temporary personnel itself, provide the records relevant to understanding the employment and client-service arrangements.
The purpose is to support a coherent explanation. A large collection of invoices and payroll files may establish that money moved without explaining why the firm considers itself principal or agent.
Review Exceptions and Changes During the Year
Contracts can change while the finance team continues using the original accounting setup. A firm that initially arranged placements might later agree to supply a managed staffing service, or it may outsource part of an existing arrangement to another provider.
Establish a process for notifying finance when commercial responsibilities change. Include new replacement commitments, revised payment terms and changes in who supplies the underlying service.
Review side letters and material email agreements where they modify the signed contract. Management should understand whether the documented terms remain current and whether the operational process follows them.
Changes do not automatically require a different revenue presentation, but they may require the assessment to be revisited. The file should explain what changed, when it changed and why the accounting conclusion remains appropriate or needs updating.
Understand the Effect on Management Reporting
Gross-versus-net presentation affects how management reads the business. Revenue per employee, revenue growth and margin percentages can look very different depending on the underlying service mix.
In the simplified examples, S$8,000 represents 16% of S$50,000 of gross revenue. For the agent, S$8,000 is its revenue before its own operating costs. Comparing those percentages without understanding the arrangements could lead to a misleading view of performance.
Use additional management measures where helpful, such as total client billings, net fee income and contribution after relevant operating costs. Label them clearly and reconcile them to the financial statements so that operational measures do not become confused with reported revenue.
When comparing periods, consider whether the mix of principal and agency arrangements changed. Lower reported revenue does not necessarily mean lower commercial activity, just as higher billings do not necessarily mean the firm earned more.
Make the Assessment Part of Contract Onboarding
The best time to identify a difficult reporting question is before a new arrangement has generated months of transactions. Give finance access to significant contracts during onboarding and agree how the activity will be recorded.
A practical review can establish the promised service, the parties involved, the evidence supporting the accounting conclusion and the records needed each month. Management should approve the conclusion and update it when the facts change.
Kazuma Public Accounting Corporation provides statutory financial statement audit services. Recruitment firms planning for their audit can help the process by presenting their principal-versus-agent assessment alongside the contracts and transaction records supporting it.
For businesses considering audit services Singapore providers offer, the central question is what the recruitment firm is responsible for providing and whether it controls that service before transfer. Once that is established, the revenue presentation should follow the substance of the arrangement, with client billings, supplier or payroll costs and fees recorded consistently.